
When a Client Requires $2M E&O: What Oakville Consultants Should Check
We provide professional insurance guidance for businesses and individuals through a secure and confidential quote process designed to be clear, efficient, and easy to begin.
Locally established in Oakville, Ontario
Coverage designed to match your business needs
Insurance options reviewed across markets and emailed to you
When a Client Requires $2M E&O: What Oakville Consultants Should Check
We provide professional insurance guidance for businesses and individuals through a secure and confidential quote process designed to be clear, efficient, and easy to begin.

Locally established in Oakville, Ontario

Coverage designed to match your business needs
Insurance options reviewed across markets and emailed to you
A new client may ask for $2 million in Errors and Omissions insurance before signing a contract or allowing work to begin. They may also request a Certificate of Professional Liability Insurance, proof of E&O coverage, or specific insurance wording during vendor onboarding.
These requirements can appear in contracts involving marketing consultants, business consultants, IT consultants, technology firms, project consultants, and other professional service providers.
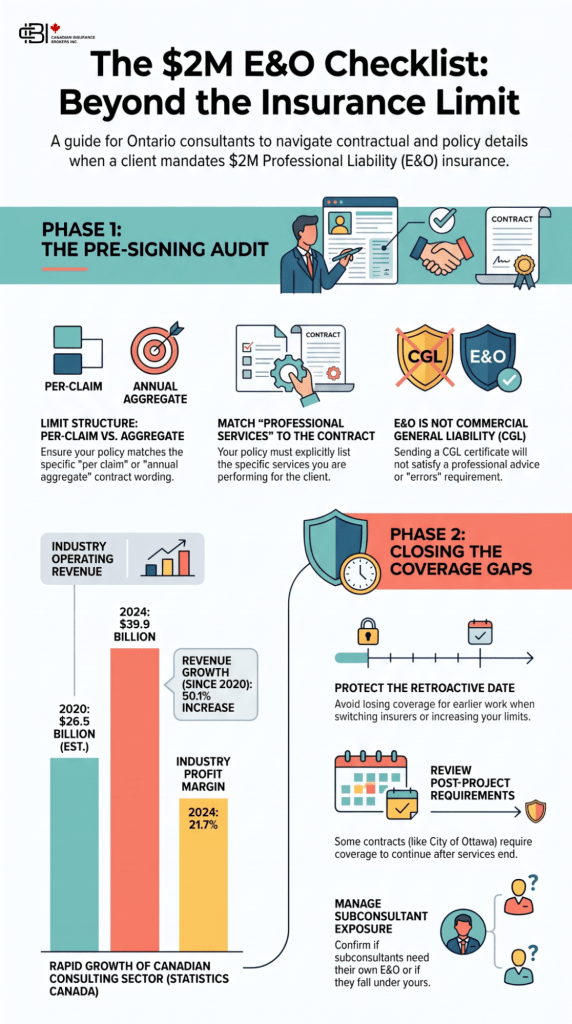
If your client says, “We need proof of $2M E&O,” do not look only at the dollar limit. Check the full insurance clause, including the required limit structure, insured services, deductible, certificate wording, retroactive date, and how long coverage must remain in force.
At a Glance
A consulting contract may trigger an insurance review when:
- A client requires $2 million professional liability insurance
- Procurement requests a Certificate of Professional Liability Insurance
- Vendor onboarding asks for proof of E&O
- A contract specifies minimum insurance limits
- A client increases its requirement from $1 million to $2 million
- A consultant starts working with a corporate or public-sector client
- New services are added to an existing contract
- A client requires coverage to continue after the project ends
The important step is to review the complete insurance clause before agreeing that your existing policy satisfies it.
Common Contract Triggers That Lead Consultants to Need E&O Insurance
Many consultants first start looking for E&O insurance because a client or contract requires it.
Common triggers include:
- “Client requires $2M E&O insurance”
- “Need proof of professional liability insurance”
- “Need Certificate of E&O insurance for contract”
- “Vendor onboarding requires professional liability”
- “Need $2 million professional liability insurance in Ontario”
- “Consulting agreement requires E&O coverage”
- “Client increased insurance requirement”
- “Need insurance before project starts”
These are often the moments when professional liability changes from an optional risk-management discussion into a contractual requirement that must be addressed before work begins.
Oakville Requires $2M Professional Liability
Oakville provides a direct example of a client imposing an E&O requirement.
Under the Town of Oakville Insurance Requirements Procedure, consultants contracted by the Town to perform professional work must carry at least $2 million in professional liability insurance, unless the contract specifies another amount.
The Town’s procedure also addresses:
- Proof of insurance
- Certificate of Insurance requirements
- Responsibility for deductibles
- Contract-specific insurance limits
This is a good example of why a consultant may suddenly need $2M E&O insurance in Ontario even if they previously worked without that level of coverage.
What Does a $2 Million E&O Requirement Actually Mean?
“$2 million E&O” may sound straightforward, but professional liability limits can be structured differently.
The PDAC Consultants Package, for example, publishes professional liability options including:
- $1 million per claim / $1 million annual limit
- $1 million per claim / $2 million annual limit
- $2 million per claim / $2 million annual limit
- $3 million per claim / $3 million annual limit
- $5 million per claim / $5 million annual limit
A policy with $1 million per claim and $2 million aggregate is not necessarily the same as a contract requiring $2 million per claim.
If the wording is unclear, send the complete clause to your broker rather than relying on the headline limit.
Do Not Stop at the $2 Million Number
The limit is only one part of the insurance clause. The surrounding wording determines whether your policy actually satisfies the client's requirement.
Required Limit: $2,000,000
Is E&O the Same as Commercial General Liability?
No. Professional liability insurance, also called E&O insurance, is designed for allegations involving professional advice or services that allegedly cause financial harm.
For consultants, allegations could involve:
- Incorrect advice
- Errors in analysis
- Missed requirements
- Failure to deliver agreed services
- Incorrect recommendations
- Professional negligence
- Errors in reports or deliverables
Commercial General Liability addresses different exposures, including certain third-party bodily injury and property damage claims.
If a client requests $2 million in E&O, sending evidence of $2 million in CGL does not necessarily satisfy the requirement.
$2M E&O Requirements for Marketing, Business and IT Consultants
The same $2 million professional liability requirement can mean very different things depending on the consulting services provided.
Marketing Consultants
Marketing consultants may provide strategy, advertising, media, branding, content, analytics, or campaign management.
E&O allegations could involve:
- Incorrect marketing advice
- Errors in campaign strategy
- Missed advertising deadlines
- Incorrect media placement
- Errors in reports or analytics
- Failure to deliver contracted services
- Alleged financial loss resulting from professional advice
A marketing consultant should make sure the professional services listed on the E&O policy match the actual services described in client contracts.
Business Consultants
Business consultants may advise clients on operations, strategy, management, processes, growth, finance, or organizational decisions.
Potential E&O allegations may involve:
- Incorrect business recommendations
- Errors in financial modelling
- Faulty operational advice
- Missed project requirements
- Errors in reports
- Project management mistakes
- Alleged financial loss following consultant recommendations
The broader the consulting mandate, the more important it is to make sure the insured professional services accurately describe the work being performed.
IT Consultants
IT consultants can face additional exposure because their professional work may directly affect systems, networks, data, and business operations.
Potential allegations may involve:
- Software implementation errors
- System configuration mistakes
- Network failures
- Data loss
- Cybersecurity recommendations
- Technology project delays
- Service interruptions
- Integration failures
- Incorrect technical advice
IT consultants should also consider whether cyber insurance is required in addition to E&O, particularly when they access client systems, manage data, provide cybersecurity services, or host technology.
Two consultants may therefore have the same $2 million E&O contract requirement but need very different insurance because their professional services and potential claims are different.
Why Does the Definition of Your Consulting Services Matter?
The professional services listed on the policy should reflect what you actually do.
For example, “management consulting” may not accurately describe a business that also performs:
- Financial modelling
- IT implementation
- Cybersecurity consulting
- Human resources consulting
- Marketing strategy
- Environmental consulting
- Technical design
- Project management
- Software development
- Regulatory consulting
If a new client contract introduces a service that was not contemplated when the policy was arranged, send the scope of work to your broker before starting the project.
What If a Client Asks for a Certificate of Professional Liability Insurance?
A client may refer to this document as:
- Certificate of Insurance
- Certificate of Professional Liability
- E&O certificate
- Proof of E&O insurance
- Proof of professional liability coverage
Before sending the certificate, check that it correctly shows:
- Legal business name
- Insurer
- Professional liability or E&O coverage
- Policy number
- Effective and expiry dates
- Required limits
- Certificate holder
- Project or contract reference where required
The Town of Oakville’s insurance procedure provides a local example where consultants performing professional work must provide a Certificate of Insurance as evidence of the required coverage.
A certificate provides evidence that insurance exists. It does not automatically alter the policy to satisfy contract requirements that are not already covered.
Three Documents Need to Tell the Same Story
A certificate can show $2 million in coverage while another important requirement is missing from the policy. Click each card to see what should be checked.
1 Contract What the Client Requires +
The contract sets out what insurance the client expects you to maintain.
Check: the E&O limit, deductible, duration, required services, proof-of-insurance requirements, and any special insurance wording.
A requirement for $2 million professional liability insurance may include conditions beyond the dollar limit.
2 Policy What You Actually Bought +
The policy determines the coverage you actually have.
Check: insured professional services, limits, deductible, exclusions, retroactive date, territory, and reporting requirements.
This is particularly important for claims-made E&O coverage.
3 Certificate What You Show the Client +
The certificate provides evidence that the professional liability insurance shown is in force.
Check: named insured, insurer, policy dates, coverage type, and limits.
A certificate showing $2 million E&O does not automatically confirm that every contractual requirement is satisfied.
SHOULD
MATCH ✓
How Much Does $2 Million E&O Insurance Cost?
Professional liability insurance pricing depends on the consulting services, revenue, employees, claims history, contract size, limit required, and geographic exposure.
Published Ontario examples suggest professional liability insurance can range from approximately $500 to $5,000+ per year, depending on the risk.
A useful industry-specific example comes from the PDAC Consultants Package, where a geological consultant reported paying $4,833 for $2 million E&O insurance before obtaining the same stated limit through the program for $1,620.
This is one industry example and should not be treated as a standard premium for every consultant.
Pricing can be affected by:
- Consulting industry
- Annual revenue
- Number of employees
- Contract values
- $2 million versus higher limits
- Claims history
- U.S. exposure
- Services performed
- Subconsultants
- Cyber exposure
- Deductible selected
A marketing consultant, business consultant, and IT consultant can therefore receive very different E&O quotes despite each needing the same $2 million limit.
Get a consultant E&O quote based on your actual services and contract requirements.
Why Should Consultants Check the Retroactive Date?
Professional liability policies are commonly written on a claims-made basis, so timing can matter.
The retroactive date can affect how far back professional services are eligible for coverage, subject to the policy wording.
Pay particular attention when:
- Replacing an existing E&O policy
- Changing insurers
- Increasing coverage from $1 million to $2 million
- Incorporating an existing consulting business
- Renewing a long-term consulting agreement
- Taking on a project connected with previous work
Avoid losing protection for earlier consulting work when making insurance changes.
Does E&O Need to Continue After the Contract Ends?
Sometimes the contract specifically requires it.
The City of Ottawa’s General Terms and Conditions for Professional Consultants provide an Ontario example. The terms require at least $2 million professional liability insurance and include requirements concerning how long claims-made coverage must remain available after services conclude.
This is why consultants should review post-project insurance requirements before cancelling or materially changing E&O coverage.
What About the E&O Deductible?
Some contracts address more than the policy limit.
A client may also specify:
- Maximum deductible
- Who pays the deductible
- Whether the consultant must disclose the deductible
- Different requirements for higher-risk projects
The Town of Oakville Insurance Requirements Procedure states that the consultant is responsible for the applicable professional liability deductible.
A higher deductible may reduce the insurance premium, but the business should still be financially able to pay it if a claim occurs.
What If You Use Subconsultants or Contractors?
Using another consultant does not necessarily remove your own responsibility to the client.
Review:
- Whether each subconsultant needs E&O insurance
- Required minimum limits
- Whether you need their Certificate of Insurance
- Whether their professional services fall within your policy
- Who owns responsibility for the final deliverable
- Contractual indemnity provisions
- Incident and claim reporting procedures
If your company signs the main client agreement, the client may still look to your business if a subconsultant makes an error.
Does a Consultant Need Professional Liability Insurance in Ontario?
Canada’s consulting industry represents a substantial professional-services market.
According to Statistics Canada:
- Management, scientific and technical consulting services generated $39.9 billion in operating revenue in 2024
- Revenue increased 6.3% from 2023
- Operating revenue increased 50.1% between 2020 and 2024
- The industry’s operating profit margin was 21.7% in 2024
For insurance purposes, increasing consulting revenue, larger projects, more employees, and work with corporate or public-sector clients can all affect professional liability exposure and contract requirements.
Does a Consultant Need Professional Liability Insurance in Ontario?
There is not one universal E&O rule that applies to every person using the title “consultant.”
For many management, marketing, business, and technology consultants, the immediate insurance requirement may come from:
- A client contract
- Vendor onboarding
- An RFP
- Procurement requirements
- A professional association
- A regulator
- A landlord or financing arrangement
Some regulated professions also have separate professional liability obligations.
If you are still setting up your consulting company, our guide on how to start a consulting business in Ontario covers registration, business structure, planning, and insurance considerations.
Oakville Consultants and Professional Services
Oakville has a strong concentration of people working in professional and business-related occupations.
- Old Oakville: 13% work in professional, scientific and technical services, while 17% work in management occupations.
- Glen Abbey: 13% work in professional, scientific and technical services, with 18% in management.
- Bronte West: 12% work in professional, scientific and technical services, while 18% work in management.
- River Oaks: 11% work in professional, scientific and technical services, with 17% in management.
- Uptown Core: 12% work in professional, scientific and technical services, while 16% work in management.
These neighbourhood percentages cover the broader professional, scientific and technical services sector rather than consultants with E&O insurance specifically. They provide a local indicator of the professional-services workforce most likely to encounter consulting contracts, vendor requirements, and professional liability discussions.
What Should Ontario Consultants Check Before Signing?
Send the Entire Insurance Clause
Do not send your broker only the sentence containing “$2 million.” The surrounding requirements can matter just as much.
Confirm Per-Claim and Aggregate Limits
Check whether the client requires $2 million per claim, $2 million aggregate, or both.
Match Your Professional Services
The services on the policy should accurately describe what you are being hired to do.
Protect the Retroactive Date
Review prior-acts protection whenever changing insurers or replacing an existing policy.
Check Post-Project Requirements
Some consulting contracts require professional liability coverage to remain in place after the work has finished.
Separate CGL From E&O
A Certificate showing $2 million in Commercial General Liability may not satisfy a professional liability requirement.
Review Subconsultants
Know whether subcontractors need separate insurance and whether you must collect their certificates.
Request the Certificate Early
Do not leave insurance compliance until the day the client expects work to begin.
Why Work With James Inwood
When a client requires professional liability insurance, the goal is not simply to obtain a certificate showing “$2M.”
James Inwood Insurance can help Ontario marketing consultants, business consultants, IT consultants, technology firms, and other professional service businesses review contract requirements, compare E&O options, confirm limits, and arrange Certificates of Insurance.
Get a quote or book a meeting with James Inwood.
Frequently Asked Questions
Do not assume an additional insured requirement used for CGL works the same way for professional liability. Send the requested wording to your broker before agreeing to it.
Once the appropriate E&O policy is in force, your broker can generally arrange a Certificate of Insurance showing the required professional liability coverage and certificate holder information. Send the client’s insurance requirements to the broker first.
Ask your broker whether the current policy can be increased or whether another structure is required. Higher limits can affect pricing and insurer availability depending on the consulting services and contract.
No. If the corporation signs a client contract requiring E&O insurance, incorporating does not remove the contractual requirement. Make sure the correct legal entity and professional services appear on the policy.

James Inwood is an Ontario insurance broker who works with consultants, professional firms, technology businesses, contractors, healthcare practices, and other commercial clients. He helps businesses review professional liability, Commercial General Liability, cyber, property, and other insurance based on their contracts and operations.
James Inwood, Insurance Broker
RIBO licensed | LinkedIn